Retirement plan advisory

Your retirement plan has two jobs. Is it doing both?

A well-built plan should do two things at once: help the owner save meaningfully on a tax-advantaged basis, and help the business attract and keep good people. Many plans are built to clear compliance - and quietly underperform on both.

3(21) plan fiduciary · Fee-based · Prefer to talk? Call 360-364-1777

PLAN REVIEWFeesInvestmentsFiduciary processParticipationThe ownerThe team
Who we work with

Two roles, two sets of stakes - one plan that has to serve both.

Whether you sponsor the plan as the owner or administer it as a CFO or HR lead, the pressures are different. The need for an advisor who shares the work is the same.

For the business owner

Your plan should work for you, not just your team.

Many plans are designed to satisfy requirements. Fewer are designed around what the owner can personally set aside - which can be well beyond the standard deferral owners often assume is the limit.

Increase owner contributions, within IRS limits
Help you manage your fiduciary responsibilities
Use the plan as a real retention tool
Coordinate it with your personal wealth strategy
For plan sponsors
For CFOs & HR leaders

You carry real liability here. Let's make the plan defensible.

As administrator, you're personally responsible for compliance, the investment menu, fee reasonableness, and documentation. Most administrators don't fully see that exposure until something tests it.

Fiduciary liability review and documentation
Investment menu evaluation and benchmarking
Fee reasonableness analysis
Enrollment support and participation
For plan administrators
What we do

Sponsoring a plan carries real risk - our job is to help you manage it.

We serve as a 3(21) fiduciary for our investment recommendations. You keep final authority over the plan, and the process behind our recommendations is documented and kept current.
01 / Governance
Plan governance
A defined process for how plan decisions get made, who makes them, and when they get revisited - so oversight runs on a schedule instead of on memory.
02 / Investments
Investment menu review
We evaluate the lineup for quality, cost, and fit, and recommend changes on a documented schedule, for your approval.
03 / Cost
Fee benchmarking
Plan fees have to be reasonable under ERISA. We benchmark total plan cost against comparable plans and show you where it stands.
04 / Owner
Owner contribution design
Many plans leave the owner's own opportunity untouched. We design the structure around what you can set aside tax-advantaged each year.
05 / People
Enrollment & education
Low participation undercuts the whole benefit. We run enrollment and education that helps the plan reach the people it's meant to.
06 / Audit
Documentation & review
Documented reviews, investment policy, vendor due diligence - the paper trail that supports the process if it's ever examined.
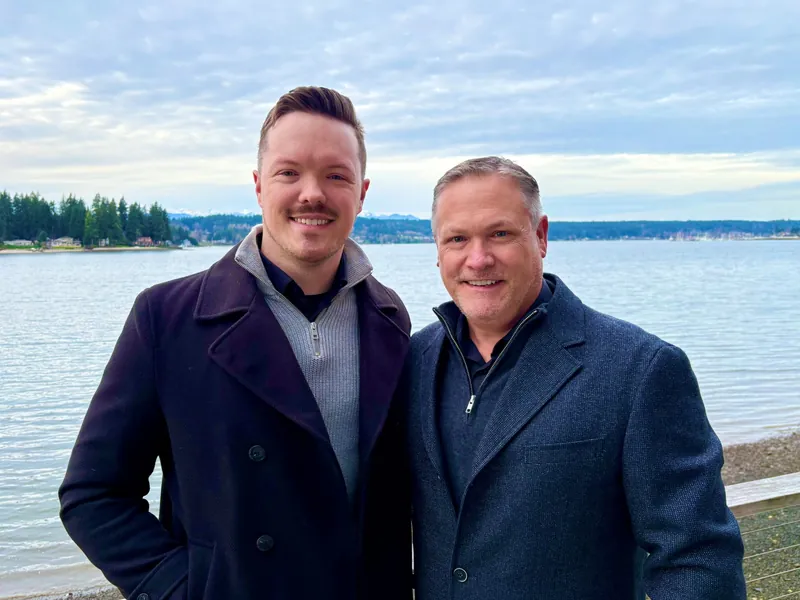
Tyler and Nate Walters by the water in Kitsap County

Who you'll work with

Nate and Tyler, start to finish.

You'll work with both of us on the plan, so it works for you as the owner and for your team. Nate has advised business owners for more than thirty-five years. Tyler brings an analytical, modern approach to every plan.

No account reps or hand-offs. When you call, you reach one of us.

Meet Nate and Tyler
What we typically see

In our experience, most plans aren't broken. They're just unattended.

The average plan does the minimum well enough. The gap between that and a well-run plan rarely shows up as a crisis - it shows up quietly, in the same few places, year after year.

A
Fees that were never benchmarked
Reasonable is a standard you have to demonstrate. "We've always used them" isn't documentation.
B
A menu no one formally monitors
Default funds, set once, reviewed rarely - and no written record of the decisions in between.
C
An owner saving less than the plan allows
The design was built for compliance, not for the person who signs for it.
“
Whether you're an owner trying to save more or an administrator trying to stay protected, a short conversation is usually enough to tell whether the plan is doing its job.
- Nate Walters, Walters Wealth Management

How it works

What working with us on your plan looks like.

It starts with a clear look at the plan you have today.

1

A review of the plan

Fees benchmarked against comparable plans, the investment menu, plan design, and the documentation on file.

2

What we found, walked through together

What's working, what isn't, and what you'd like the plan to do for you and your team.

3

Recommendations in writing

Changes to the menu, owner contribution design and plan governance, coordinated with your recordkeeper and TPA.

4

Ongoing support

Documented reviews, investment monitoring, and enrollment and education for your team.

Start here

Find out what your plan is - and isn't - doing.

A 30-minute review is enough to see where a plan stands and what a better-built one could do for you and your employees.

Book a 30-minute plan review

A straightforward look at whether your plan is working as hard as it should.