For plan sponsors
You sponsor the plan, so you carry the most exposure and stand to gain the most from it. Yet owner-sponsored plans are usually built to clear compliance - not to make the most of what you personally set aside or reduce the liability that sits on your name.
That gap - roughly $47,500 a year for 2026 - can be contributed on a tax-deferred basis, depending on plan design, compensation and testing. In our experience, many plans don't capture it because they weren't designed to.
Figures reflect 2026 IRS limits: $24,500 employee elective deferral and a $72,000 total annual-additions limit (higher with age-50+ catch-up contributions). Limits change annually, and your actual maximum depends on plan design, compensation, and age. This is a hypothetical example for illustrative purposes only and should not be considered as specific tax advice. You should consult a legal or tax professional regarding your individual situation.
Getting an owner well past the standard deferral isn't a trick - it's deliberate plan design. Three levers do most of the work, layered to fit your income and your goals.
As plan sponsor, you're a fiduciary under ERISA, and individuals who act as plan fiduciaries, often owners and officers, can be held personally responsible for plan losses, unreasonable fees, and compliance failures. That exposure often isn't clear until something tests it.
We serve as a 3(21) investment fiduciary to the plan. You keep final authority and remain the decision-maker - but our recommendations are held to a fiduciary standard, and the governance behind them is documented and monitored.
Who you'll work with
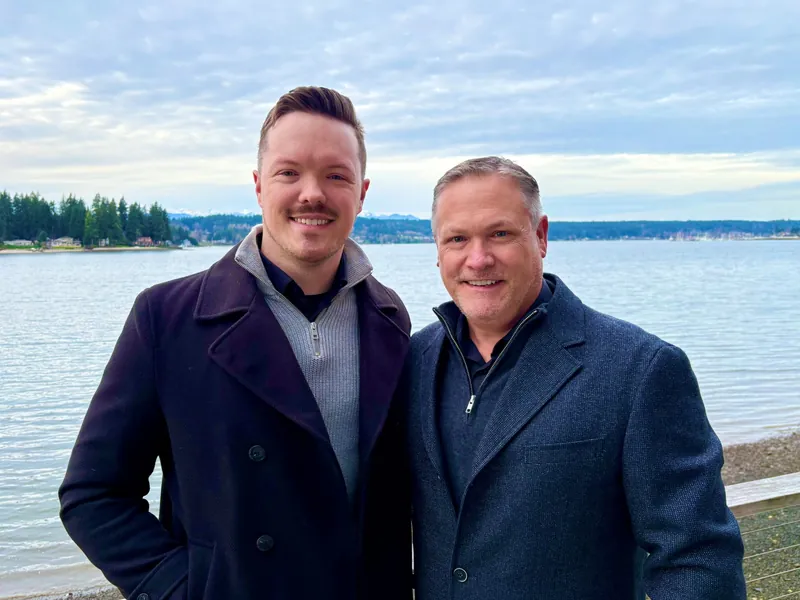
You'll work with both of us on the plan, with an eye on what it does for you personally as the owner and sponsor. Nate has advised business owners for more than thirty-five years. Tyler brings an analytical, modern approach to every plan.
No account reps or hand-offs. When you call, you reach one of us.
Meet Nate and TylerThe plan shouldn't serve only your employees. We help design it so it works just as hard for the person who signs for it.
How it works
It starts with a clear look at the plan in your name.
Fees, the investment menu, plan design, and where your personal fiduciary exposure sits today.
How profit sharing, safe harbor and enhanced plan design could raise what you personally put away, within IRS limits.
Design changes, menu changes and fee negotiations, coordinated with your recordkeeper and TPA and lined up with your personal wealth.
Investments reviewed quarterly, governance kept in writing, and enrollment support for your team.
Many aren't. Thirty minutes is enough to see if you're leaving anything on the table - and what a better-built plan could do for you.
Find out what you're leavingA straightforward look at whether your plan is working as hard as it should.