Fiduciary guide
ERISA is specific, consequential, and routinely misunderstood. This guide covers what fiduciary responsibility really requires, who carries it, and where plans most often quietly fall out of compliance.
A fiduciary is someone the law requires to act in another party's best interest - here, the participants in your retirement plan. ERISA established a strict fiduciary standard for employer-sponsored plans in 1974, and it remains one of the most rigorous standards in American law.
The fiduciary standard requires every decision to be made in the exclusive best interest of participants. Fees must be reasonable. Investments must be prudent. The process must be documented. And it's ongoing and active - not a one-time designation you can set and forget.
The part owners most often miss: individuals who act as plan fiduciaries can be held personally liable for breaches.
ERISA defines fiduciaries by what they do, not by their title. Anyone who exercises discretion over how the plan is managed or run, controls its assets, or gives the plan investment advice for a fee is a fiduciary, whether or not they realize it. That usually includes:
ERISA sets four duties every fiduciary must meet. These aren't aspirational - they're legal obligations with personal liability attached.
Every decision must be made solely in the interest of participants and beneficiaries. Your interests as employer - and your providers' interests - are legally subordinate.
You must act with the care and skill a "prudent expert" would use. Ignorance is no defense - you're expected to have the expertise or hire someone who does.
Plan assets must be diversified to minimize the risk of large losses, unless it is clearly prudent not to under the circumstances.
Fiduciaries must act in accordance with the governing plan documents - provided those documents themselves comply with ERISA.
We serve as a 3(21) fiduciary to the plan. Here is how the roles divide.
Investment recommendations held to a fiduciary standard, with the process behind them written down and kept current.
Final authority over the plan stays with you, and you remain the decision-maker.
These are what we most often find on a first plan review. Each one is real liability sitting with the plan's fiduciaries right now.
In a DOL audit, documentation is everything. These are the records that protect you - and the gaps we most commonly find on review.
Who you'll work with
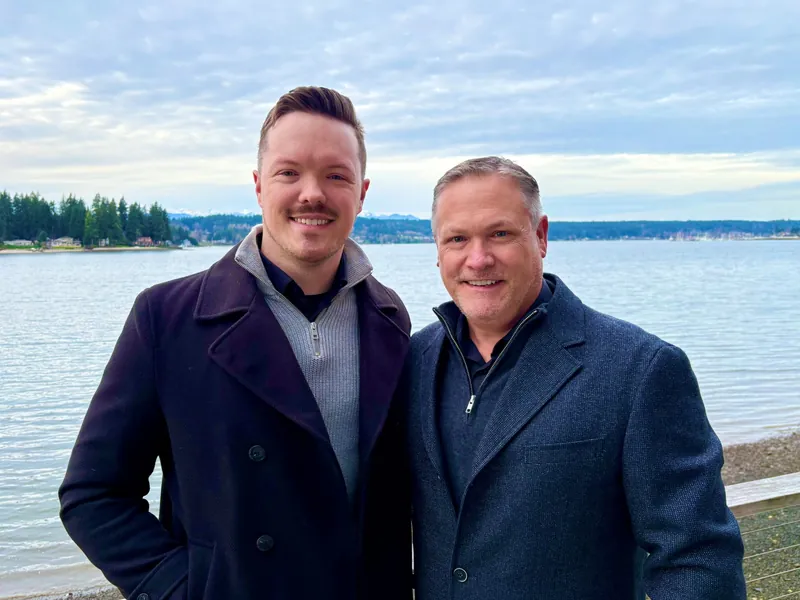
You'll work with both of us on your plan's fiduciary process, documented and kept current. Nate has advised business owners for more than thirty-five years. Tyler brings an analytical, modern approach to every plan.
No account reps or hand-offs. When you call, you reach one of us.
Meet Nate and TylerA 30-minute conversation is enough to see what your plan needs.
Make it manageableA straightforward look at where your plan stands.