Protecting your family and business
Estate planning that helps protect your family and your business.
If something happened tomorrow, would everyone be ready? For a business owner, an estate plan has more to carry: a company that needs someone to run it, partners who need clarity, and a family that may need cash quickly. We help you see where things stand, and work alongside your attorney so the plan holds together.
The pieces of a plan
What a business owner's plan usually includes.
Each piece is drafted or handled by the right professional. What matters is that they agree with each other, and with what the business is worth today.
Wills and trusts
Who receives what and who's in charge, and for married couples, whether a trust could make use of both spouses' Washington exclusions. Drafted by your estate attorney.
Buy-sell agreement
Who can buy an owner's share, at what price, and how it's paid for. An older agreement may name a value the business has since outgrown.
Buy-sell agreementsLife and key-person insurance
We offer coverage directly and help size it to what your family relies on from the business, plus the cash a buyout or estate tax may require.
Powers of attorney
Who can make financial and business decisions if you're alive but unable to, so the business doesn't stall.
Instructions for the business
Who runs it, who to call, where things are kept, and whether it continues or is sold. A piece that often lives only in the owner's head.
Titles and beneficiaries
How accounts and business interests are owned, and who they name. These can override a will, so they need to match the plan.
Who depends on you
Many people depend on your plan.
When an owner can no longer work, the effects reach well beyond the household. A good plan has an answer for each of them.
Your family
Income to live on, time to make good decisions, and cash for expenses and taxes that can come due quickly.
Your business
Someone to run it and keep customers confident, and clear instructions on whether it continues or is sold.
Your partners
A current buy-sell agreement, a fair way to value your share, and a way to pay for it.
Your team
People who know what happens next, and a business that can keep paying them.
Washington's estate tax
Washington's estate tax starts far below the federal level.
Because the business counts toward the estate, a Kitsap owner can reach Washington's threshold sooner than expected. And the tax is due nine months after death, often before a business could be sold.
The exclusion: Washington vs. federal
For deaths on or after July 1, 2026.
Washington's $3,000,000 exclusion applies to deaths on or after July 1, 2026, with rates from 10% to 20% on the amount above it, and it doesn't pass to a surviving spouse. Sources: Washington State Department of Revenue; IRS.
The nine-month clock
Washington and federal estate tax are both due nine months after death.
In some cases, Washington allows tax on a closely held business to be paid in installments, with interest.
Estimate your estate taxAn example
What the nine-month clock can look like.
Here's how Washington's estate tax could play out for a Kitsap owner whose business is most of the estate.
A $6 million estate and a nine-month deadline
The assumptions
- OwnerSingle
- The owner's share of the business$4,000,000
- Everything else (home, savings, retirement)$2,000,000
- Date of deathOn or after July 1, 2026
- ResidencyWashington resident, U.S. citizen
- Lifetime taxable giftsNone
- Other deductionsNone assumed
Estimated estate tax
The question for the family is where $390,000 would come from within nine months, while the business still needs to run. Ways owners plan for it:
A hypothetical illustration based only on the assumptions shown. It is not a projection or guarantee of results for any client, and it is not tax or legal advice. Estimated with our estate tax calculator, using Washington Department of Revenue and IRS figures.
How we help
Your attorney drafts the plan. We bring the financial side.
We don't draft legal documents or give legal advice; that's your estate attorney's work, and it's essential. Our part is the financial side, so the documents reflect what you own today.
Gather the full picture
What the business may be worth today, what you own personally, and the documents already in place.
Check that it all agrees
Values that may have changed, beneficiaries, and whether the buy-sell and the will point the same direction.
Plan for the cash
Where money for taxes, a buyout, and the family's expenses would come from, and how quickly. Where insurance fits, we can put it in place.
Work alongside your attorney
With your permission, we share the financial picture so any updates happen in one coordinated step.
If you're looking for an estate attorney, we're glad to share the names of professionals we know and trust.
Who you'll work with
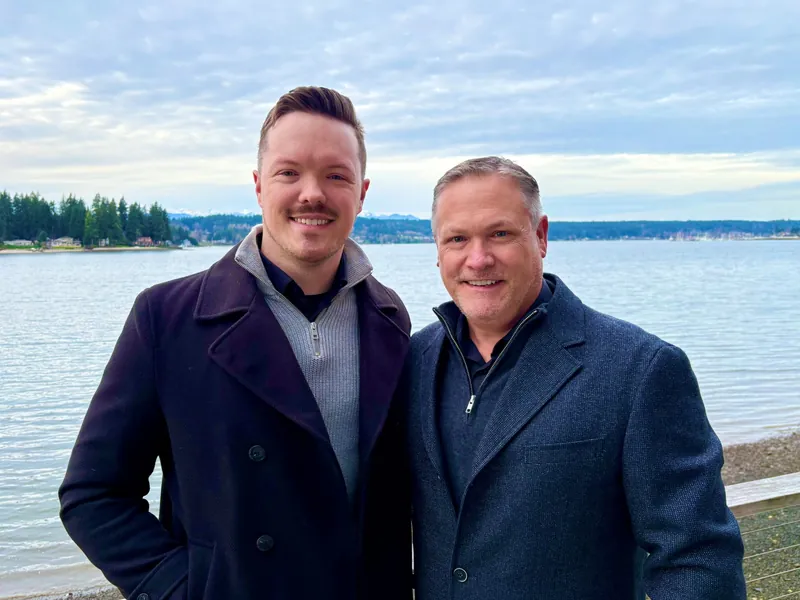
Nate and Tyler, start to finish.
You'll work with both of us, alongside your estate attorney, so the plan protects your family and the business. Nate has advised business owners for more than thirty-five years. Tyler brings an analytical, modern approach to every plan.
No account reps or hand-offs. When you call, you reach one of us.
Meet Nate and TylerQuestions owners ask
Common questions about estate planning.
How much is Washington's estate tax exclusion?
For deaths on or after July 1, 2026, Washington's exclusion is $3,000,000, and the amount above it is taxed at rates from 10% to 20%. The federal exclusion for 2026 is $15,000,000 per person.
Does Washington's exclusion pass to a surviving spouse?
No. Unlike the federal exemption, Washington's exclusion isn't portable, so it can go unused at the first death unless the estate plan is set up to use it, often with a trust. An estate attorney can advise on what fits your family.
When is Washington estate tax due?
Nine months after the date of death, the same as federal estate tax. In some cases, tax on a closely held business can be paid in installments, with interest.
Do you offer insurance?
Yes. We offer life and key-person insurance directly, and help size coverage to what your family and business would need, including the cash a buyout or estate tax may require.
Do you draft wills or trusts?
No. An estate attorney drafts the documents and provides legal advice. We bring the financial side, and with your permission we work with your attorney so the plan reflects what you own today.
Related guides
Browse all resourcesThis page is general educational information, not tax, legal, or investment advice. Walters Wealth Management does not provide tax preparation or legal services. Please talk with your estate attorney or CPA about how any strategy applies to you.
Make sure your plan still fits the business you've built.
A 30-minute conversation is enough to see where your plan stands and what, if anything, needs attention.
We work alongside your attorney, never in place of them.