Tax strategy for business owners
Tax planning for business owners, before the year closes.
Business owners have more tax decisions than most people: how you're paid, how the business is set up, when income lands, and how much goes into a retirement plan. We help you see them coming, and work alongside your CPA so they're decided ahead of time.
Where an owner's taxes are shaped
The decisions behind an owner's tax bill.
For a Kitsap business owner, much of the tax year is settled by choices made well before April. These are the ones we look at together, every year.
How you pay yourself
The mix of salary and distributions affects payroll taxes, how much you can put into a retirement plan, and how a buyer may look at the business someday.
Your retirement plan
A plan designed with the owner in mind can allow larger pre-tax contributions than a standard setup. Whether it fits depends on your age, income, and team.
Cash balance plansWhen income and expenses land
Owners often have some say over the timing of income, bonuses, and large purchases. That flexibility is most useful when it's planned before year-end.
How the business is set up
Entity type affects how profits are taxed today and what options you'll have at a sale. It's worth revisiting as the business grows, with your CPA and attorney.
Washington's own taxes
A capital gains tax on a sale, an estate tax that starts well below the federal level, and a new 9.9% income tax above $1 million scheduled for 2028, though Initiative 645 on the November 3, 2026 ballot and a pending court challenge could change that.
Washington law changesGiving, to family and to causes
Gifts can be timed and structured with taxes in mind, especially in a year when income runs high.
An example
What planning ahead can change.
Some of the largest tax differences for Kitsap owners come from decisions made years before a sale.
One sale, two very different Washington tax bills
The assumptions
- Sale price$5,000,000
- Cost basis$500,000
- Deal costs6% ($300,000)
- Filing statusMarried, filing jointly
- Year of sale2026
- Type of saleStock or LLC interest
- The gainAll long-term
- The $0 caseAssumes every deduction requirement is met
Estimated Washington capital gains tax
Washington lets an owner deduct the gain from selling all or substantially all of a qualifying family-owned business. Several requirements depend on history, like owning the business for at least five years and you or a family member working in it at least five of the ten years before the sale, so they're worth checking well in advance.
A hypothetical illustration based only on the assumptions shown. It is not a projection or guarantee of results for any client, and it is not tax or legal advice. Estimated with our business sale calculator, using the 2025 Washington standard deduction ($278,000), the latest published.
Working together
Your CPA and us: different jobs, one plan.
We don't prepare tax returns or give legal advice. Your CPA's expertise is essential, and we don't try to replace it. Our part is the planning around it.
Your CPA
- Prepares your business and personal tax returns
- Advises on tax law and how it applies to you
- Handles filings, notices, and questions from tax authorities
Walters Wealth Management
- Projects income and taxes through the year
- Designs retirement savings around the owner
- Times investment and income decisions with taxes in mind
- Shares projections with your CPA through the year, with your permission
If you're looking for a CPA, we're glad to share the names of professionals we know and trust.
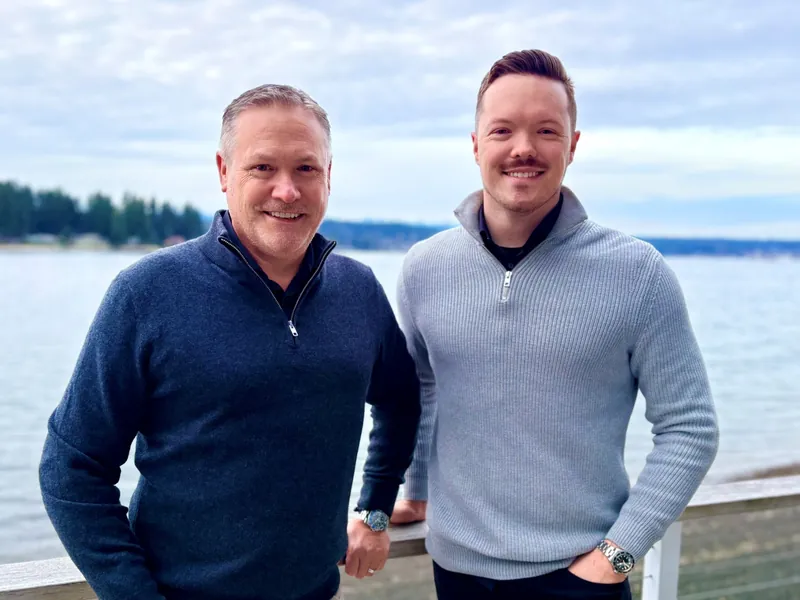
Who you'll work with
Nate and Tyler, start to finish.
You'll work with both of us, alongside the CPA you already trust, to plan the tax year before it closes. Nate has advised business owners for more than thirty-five years. Tyler brings an analytical, modern approach to every plan.
No account reps or hand-offs. When you call, you reach one of us.
Meet Nate and TylerPlanning ahead
An owner's tax year, planned ahead.
By the time a return is prepared, most of the year's decisions have already been made. Planning through the year keeps more of them open.
Set the year's goals
Look at last year's results and decide what this year needs to do: income, savings, and any big events ahead.
Check the projection
See how income is tracking and whether anything has changed: a strong year, a large purchase, a sale on the horizon.
Make the year-end decisions
Retirement plan contributions, timing of income and expenses, and any gifts, decided while there's still time to act.
File with the year already planned
Your CPA prepares the return, with the year's decisions already made and documented.
An illustration of a typical planning rhythm. The timing for your situation may differ.
Before December 31
A big year, or a business that keeps growing? There's still time.
When income is up, whether from one exceptional year or steady growth, some of the most valuable decisions have to be made before the year closes. Others set up the years ahead.
Before this year ends
- Retirement plan contributions. How much you and the business can still put away, and whether a plan you don't have yet could still count for this year.
- Timing of income and expenses. Equipment, vehicles and other purchases the business already needs, and when income lands, can shift which year carries the tax.
- How you pay yourself. The mix of salary and distributions, and whether it still fits a business that has grown.
- Giving. For owners who already give, a larger gift in a high-income year, including through a donor-advised fund, can go further.
As the business keeps growing
- A retirement plan for the next stage. A plan that fit a small team can cap what the owner saves. A cash balance plan alongside a 401(k) can raise it substantially.
- Structure. Whether the way the business is set up still makes sense at today's income, reviewed with your CPA.
- Washington's new income tax. Rising income may reach the 9.9% tax on income above $1 million starting in 2028, pending Initiative 645 and a court challenge. See if it would apply.
- Wealth outside the business. Growth usually means reinvesting. Deciding how much of each good year to build outside the company keeps one asset from carrying everything.
General information, not tax or legal advice. We coordinate every decision with your CPA, who prepares your return.
The big years
When a big tax year is coming.
Some years carry more weight than others. These free calculators give you a first look, using official IRS and Washington figures.
Selling your business?
Business Sale Calculator
What you'd keep after federal and Washington taxes.
Estimate your net proceedsPlanning your estate?
Estate Tax Calculator
What Washington and federal estate tax could cost your family.
Estimate your estate taxExpecting a big income year?
Millionaires' Tax Calculator
Whether Washington's new 9.9% income tax would apply to you.
Estimate your income taxQuestions owners ask
Common questions about tax planning.
Do you prepare tax returns?
No. Walters Wealth Management doesn't prepare tax returns or provide tax or legal advice. We work alongside your CPA, or one you choose, on the planning side: projections, retirement plan design, and the timing of decisions, so the return reflects choices made ahead of time.
When should an owner start planning for this year's taxes?
Early. Some of your tax decisions, like how you're paid, the timing of income and large purchases, and certain retirement plan elections, have year-end deadlines. Starting early in the year leaves the most options open.
Does Washington have an income tax?
Not today, on wages or other ordinary income. Washington taxes long-term capital gains at 7% above a standard deduction ($278,000 for 2025) and 9.9% on taxable gains above $1 million; real estate is exempt. A new 9.9% tax on household income above $1 million is scheduled to begin in 2028, though Initiative 645 on the November 3, 2026 ballot and a pending court challenge could change that.
Can a retirement plan lower an owner's taxes?
It can. Contributions to qualified retirement plans are generally made before tax, and some designs, such as a cash balance plan alongside a 401(k), allow larger contributions than a standard plan. Whether one fits depends on your age, income, and employees.
Do you work with owners who already have a CPA?
Yes. With your permission, we share projections and plans with your CPA through the year, so everyone is working from the same numbers.
Related guides
Browse all resourcesThis page is general educational information, not tax, legal, or investment advice. Walters Wealth Management does not provide tax preparation or legal services. Please talk with your CPA or attorney about how any strategy applies to you.
The best time to plan a tax year is before it ends.
A 30-minute conversation is enough to see which decisions are still open for you this year.
We work alongside your CPA, never in place of them.